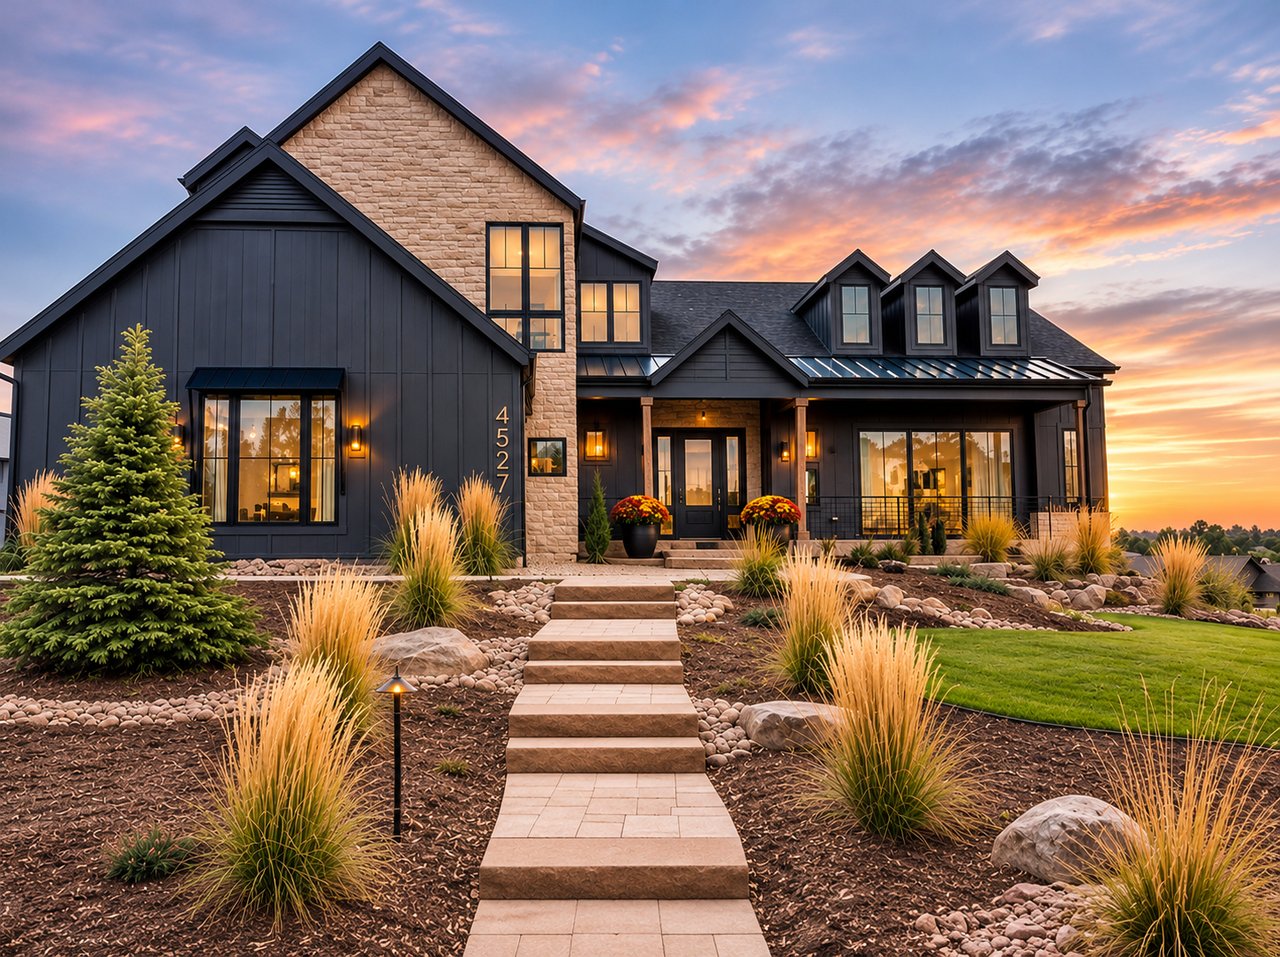
Watch out! That killer builder interest rate might come with a few surprises.
If you've been shopping for a home around the Denver metro area lately, you have probably noticed some of the deals builders are offering. Holy Smokes! Some of those mortgage rates are extremely attractive!
Large production builders often have their own mortgage companies or preferred lending partners, giving them the ability to offer financing incentives that are nearly impossible for resale sellers to compete with. We are talking about significantly reduced interest rates, sometimes permanently fixed for 30 years, along with closing cost assistance and other incentives.
Throw in a beautiful brand new house, modern finishes, and a warranty, and it is pretty damn easy to see why buyers are inerested. Trust me, I get it. There are some genuinely great opportunities in new construction right now, and Brad and I would never discourage someone from considering them.
However, there is something I wish more buyers understood before falling in love with the model home...something too many agents aren't discussing with their buyers.
The price of buying a house and the cost of owning it are two VERY different things.
First of all, those interest rates deserve a closer look. I'll give you a couple quick examples.
Let’s look at a few actual Denver-area examples. Shea Homes is advertising a 2.50% first-year payment rate at Lyric in Lone Tree, while Trumark Homes is promoting a 2.75% first-year rate at Sterling Ranch. Those numbers are pretty freaking incredible, but both offers involve temporary buydowns on adjustable-rate mortgages.
Meanwhile, Taylor Morrison is advertising a 4.99% permanent 30-year fixed rate on select Denver-area homes. These are legitimate opportunities, and some buyers could save a substantial amount of money. The important thing is understanding exactly which rate you’re getting, how long it lasts, and what your payment could look like down the road.
Is the rate permanent? Does it change after a year, two years, five years? Are there additional lender fees? What happens to your payment if the rate adjusts? What happens if you elect to refinance in the next year or two?
A great interest rate can save you a substantial amount of money. Make sure you are comparing the entire financing package, not simply the number printed in giant letters on the sales flyer.
Second, your property taxes might be a BIG surprise.
This is one of my biggest concerns with new construction in Colorado. The property tax estimate you're initially shown may not reflect what you will actually pay once the home is completed and fully assessed. Depending on the assessment cycle, the existing tax bill might reflect vacant land or an unfinished property.
Then there are metro districts. 😣
Metro discticts help finance infrastructure and amenities in many newer communities, but they can also add significantly to your property taxes. They aren't inherently bad, and some provide wonderful benefits. However, you need to understand what you are paying for and what your payments are going to look like now and for the forseeable future.
For example, Lyric at Ridgegate publishes an estimated property tax rate of approximately 1.11% of the home's sales price, along with HOA assessments of $240/month. On an $800,000 home, that is approximately $740/month in property taxes plus the $240 HOA assessments. Nearly $1000 a month before you have paid a dime toward your mortgage, insurance, utilities, or maintenance.
Sterling Ranch provides another example. One of its metropolitan districts published a 2026 budget with more than 95 mills in combined debt-service and operating levies. That is not the total tax rate for every home in Sterling Ranch, but it illustrates why buyers need to review the actual tax obligations for the specific home they're considering.
A low mortgage rate isn't nearly as exciting when your monthly escrow payment increases because the original tax estimate was far too low.
Congratulations on your new home! Now you need landscaping.
Have you ever toured a gorgeous model home with beautiful landscaping, a perfectly manicured lawn, and an outdoor living area that looks like something straight out of a magazine? Then you buy your house and discover your backyard is...dirt. Lots and lots and lots of dirt.
Depending on the builder and community, landscaping, irrigation, fencing, and other exterior improvements may be your responsibility. Those expenses can add up quickly, and some communities require landscaping to be completed within a specific timeframe.
Then there are window coverings. Blinds or shades for an entire house aren't cheap, especially when you realize how many windows your beautiful home actually has.
Add garage storage, lighting, and all the other little things you assumed were included, and suddenly yo've spent thousands of dollars beyond your purchase price. Some of those improvements may make your home more enjoyable, but dont assume you will recover every dollar when you sell.
What happens if life changes and you need to move sooner than anticipated?
This is the part I REALLY want buyers to consider.
Nobody purchases a home expecting to sell it eighteen months later. Yet, jobs change, relationships change, families change, and sometimes life throws us curveballs.
Imagine buying a brand-new home with an incredible builder-financed mortgage rate. You're happy with your payment, love your house, and everything is wonderful. Then BOOM, two years later, something unexpected happens and you need to sell. Unfortunately, the builder down the street is still selling brand new homes, and they're offering new buyers the same attractive financing incentives you received. How do you compete with that?
Looking Glass in Parker offers a useful example. Dream Finders Homes has advertised price reductions of approximately $43,000 to $58,000 on select quick-move-in homes in The Reserve at Looking Glass.
Those are advertised reductions, not proof that every home's market value has declined. Imagine trying to sell your nearly new home while the builder is offering comparable brand-new inventory at discounted prices, potentially with financing incentives on top of those reductions.
You can't offer buyers the same mortgage deal you received. You've already spent money on landscaping and window coverings, and now you have selling expenses to consider. If values haven't appreciated enough, you could find yourself bringing money to closing rather than walking away with equity. In some situations, you could even owe more than the home is worth.
That doesn't mean buying new construction is a bad investment. It means your potential exit strategy deserves just as much consideration as your purchase.
One more thing! The builder represents the builder.
The friendly salesperson at the model home may be absolutely wonderful, but they work for the builder. Builder contracts can differe significantly from resale contracts, and buyers need to understand deadlines, deposits, construction delays, inspections, and warranty provisions.
Having your own experienced real estate agent (Brad and ME) involved from the beginning can make a meaningful difference. Ideally, that means BEFORE your very first visit to the sales office, since some builders have specific requirements regarding outside agent representation.
Yes, even brand-new homes should be independently inspected. New doesn't automatically mean perfect. Trust me!!
Soooo...should you guy a new construction home?
Absolutely, if it makes sense for your situation!
There are plenty of reasons to love a new home. Modern construction, updated finishes, warranties, and attractive financing can make new builds an excellent choice, particularly if you are planning to stay for several years. Just remember the monthly mortgage payment is only part of the equation.
Property taxes, metro district obligations, HOA fees, landscaping, window coverings, upgrades, and potential resale challenges all deserve consideration BEFORE you sign a contract.
When Brad and I work with buyers, our goal is not to steer them toward new construction or resale. Our goal is to help them understand the advantages, disadvantages, and potential surprises so they can make a decision they will still feel good about years from now.
Sometimes the new build wins. Sometimes the resale home makes more sense. Sometimes the timing isn't right for either and renting is their best bet for the time being.
The best deal isn't necessarily the house with the lowest advertised interest rate. The best bet is the house that makes the most sense for your finances, lifestyle, and future.
Go ahead, call us when you want to tour those beautiful model homes and we will happily join you! Enjoy the shiny kitchens, prestine bathrooms, and incredible financing offers. We'll make sure you're looking beyond the shiny stuff. I promise you, discovering the surprises AFTER closing will be incredibly frustrating and, in some instances, life-altering.
NOTE: Builder incentives and community estimates referenced here were advertised or published as of November 2026 and are subject to change. Financing terms vary by home, lender, and buyer qualifications. Property taxes and district obligations should always be verified for the specific property.
